

Roth conversions and when they may make sense
A Roth conversion moves money from a traditional pre tax retirement account into a Roth account. You generally pay tax on the converted amount in the year of the conversion. The idea is to pay tax now, at a known rate, so qualified withdrawals later can be tax free under current rules.
It is a planning tool, not a default
Conversions can help in some years and create unnecessary tax in others. The decision depends on today’s tax rate, your expected future rates, other income, Medicare considerations, and whether you can pay the tax from non retirement funds. We coordinate with your tax advisor before any move.
Two situations that often open a window
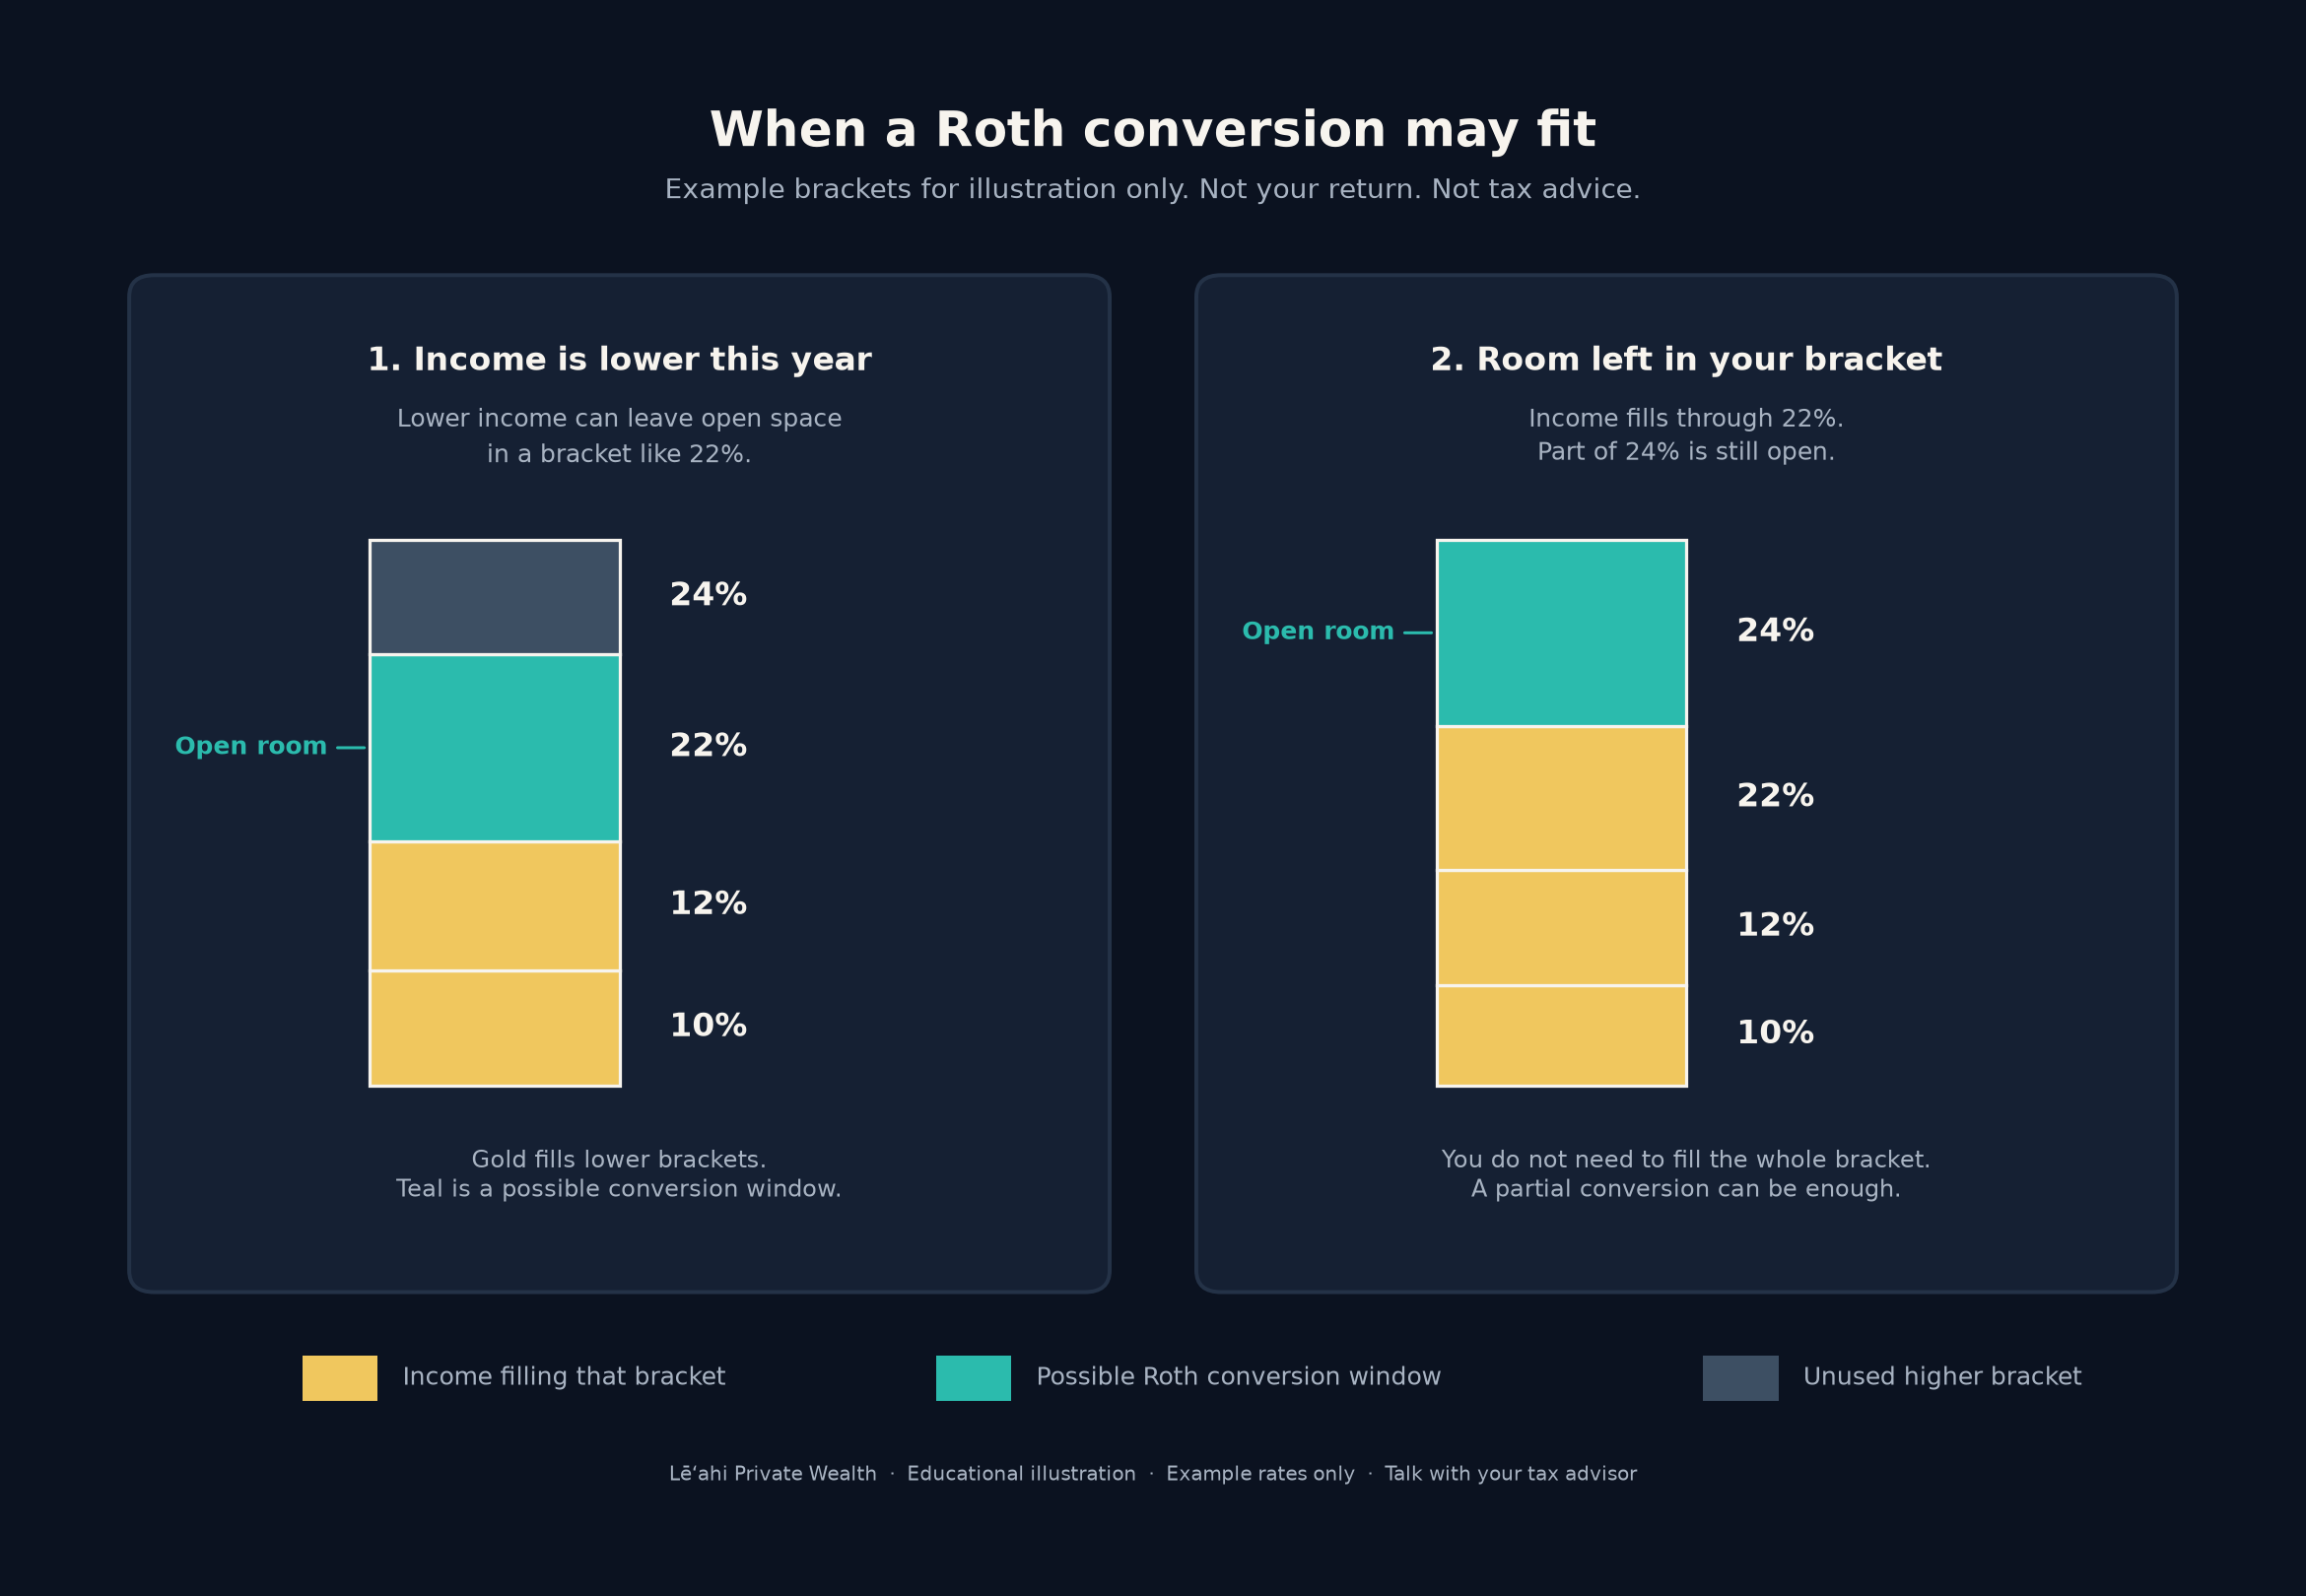
Situation A: Income drops. A lower earnings year, a business transition, a sabbatical, or early retirement before Social Security and required withdrawals begin can leave unused room in current tax brackets.
Situation B: Room left in your existing bracket. Your ordinary income fills only part of a bracket. The unused dollars up to the top of that bracket can be a measured conversion opportunity, if it still fits the rest of your plan.
See the illustrative chart on this page for a simplified picture of both situations. It is an example layout, not your tax return.Other questions we walk through
Can you pay the tax without raiding the IRA? Will the conversion affect Medicare premiums or other thresholds? How does this fit multi year planning, not just one April?
FAQ
Is a Roth conversion always smart in a down market?
Not always. A lower account value can mean converting more shares for the same tax cost, but your income, brackets, and cash to pay tax still drive the decision.
Do you prepare my tax return?
No. We analyze conversion scenarios in your financial plan and coordinate with your CPA or tax preparer.
Author: Christian Park, Managing Advisor, Lēʻahi Private Wealth
Educational information only. Not tax or personalized investment advice. Tax laws change. Coordinate with your tax advisor. Advisory services offered through Kingswood Wealth Advisors (KWA), an SEC registered investment adviser. Securities services offered through Kingswood Capital Partners, LLC (KCP), member FINRA/SIPC.